
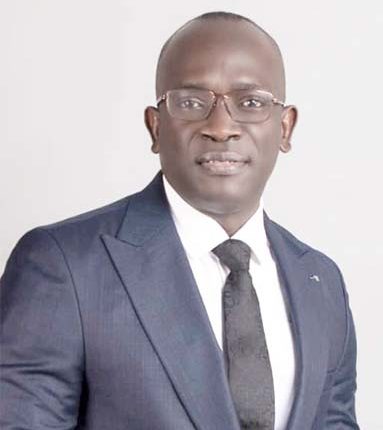
The Director-General of the Nigeria Employers’ Consultative Association (NECA), Adewale Oyerinde, has urged Nigerian businesses to embrace Environmental, Social and Governance (ESG) reporting as a strategic tool for attracting investment, strengthening competitiveness and creating jobs.
Oyerinde, who made the call while delivering the keynote address at the 2026 Annual Workshop and Awards of the Commerce and Industry Correspondents Association of Nigeria (CICAN) in Lagos, said ESG compliance was increasingly becoming a major consideration for investors, lenders, customers and international trading partners.
He explained that businesses could no longer compete solely on the basis of the quality, price and location of their products or facilities, as stakeholders were increasingly interested in their environmental practices, treatment of workers, corporate governance and long-term sustainability.
Using the example of a prospective house buyer, Oyerinde said people now looked beyond the size, location and price of a property to establish whether its structure was safe, its utilities functional and its ownership documents genuine.
He said investors and other business stakeholders were asking Nigerian companies similar questions about their operations, sustainability and ability to retain value.
According to him, the challenge before Nigeria is how to implement mandatory ESG reporting in a manner that attracts investment, protects business competitiveness and creates employment opportunities.
ESG reporting deadline draws closer
The NECA chief said the clock was already ticking for Nigerian businesses, pointing to regulatory timelines established by the Financial Reporting Council of Nigeria (FRCN) and the Securities and Exchange Commission (SEC).
He noted that the FRCN unveiled its amended roadmap and sustainability reporting guidance in February 2026 for the adoption of the International Financial Reporting Standards (IFRS) S1 and S2.
Under the roadmap, public interest entities, including all listed companies, are expected to commence reporting under the standards for financial periods beginning on or after January 2028, while small and medium-sized business entities are scheduled to follow from January 2030.
He also referenced the SEC’s circular of September 21, 2026, which required public companies and significant capital market operators to submit their adoption plans, gap assessments and board oversight arrangements by October 15, 2026.
According to Oyerinde, the requirements mean that preparation for ESG reporting has already become a compliance obligation for listed companies.
He further observed that the development was part of a global trend, noting that nearly 50 jurisdictions were on the path to adopting the IFRS sustainability standards, while companies in 13 jurisdictions had already applied them for the 2025 financial year.
Carbon regulations threaten export competitiveness
Oyerinde also warned that international environmental regulations were creating additional pressure on Nigerian exporters, particularly those seeking access to European markets.
He cited the European Union’s Carbon Border Adjustment Mechanism (CBAM), which entered its definitive phase in January 2026, covering imports of products such as cement, iron and steel, aluminium, fertilisers, hydrogen and electricity.
He explained that the mechanism requires importers to account for the carbon emissions embedded in covered products, making reliable emissions data increasingly important for exporters.
He warned that where suppliers could not provide verified emissions information, higher default emissions values could apply, potentially increasing the cost of their products.
“For Nigerian exporters, carbon data now affects both price and market access,” he said.
Oyerinde explained that IFRS sustainability standards require businesses to disclose sustainability-related and climate risks that could affect their cash flows, financial positions and cost of capital.
He said manufacturers would need to demonstrate how energy costs and climate risks affected their earnings, while banks would have to assess climate-related exposure within their loan portfolios.
Exporters, he added, would also need to meet the carbon, labour and other sustainability requirements of international customers.
ESG presents investment and job opportunities
Despite the compliance challenges, the NECA director-general identified opportunities in ESG adoption, particularly in access to finance, international markets and employment generation.
On financing, he said credible sustainability disclosures could improve businesses’ ability to attract investment, especially as Nigeria requires substantial capital to finance its energy transition.
He cited Nigeria’s Energy Transition Plan, which estimates that the country needs approximately $410 billion in additional investment to achieve its energy transition ambitions by 2060, representing about $10 billion annually.
He said companies with reliable ESG data would be better positioned to attract some of the capital required for the transition.
On market access, Oyerinde said businesses capable of documenting their emissions, labour practices and corporate governance standards would be better placed to participate in European and global supply chains, as well as opportunities under the African Continental Free Trade Area (AfCFTA).
He also identified renewable energy, recycling, waste management, energy efficiency and cleaner production as emerging growth areas with significant employment potential.
According to him, Nigeria’s Energy Transition Plan projects the creation of up to 340,000 jobs by 2030 and 840,000 by 2060 if the programme is successfully implemented.
NECA seeks phased ESG implementation
However, Oyerinde cautioned that the cost of compliance could place additional pressure on businesses already struggling with high operating expenses and infrastructure deficiencies.
He called for a practical and phased approach to ESG implementation that would recognise the different capacities of large corporations and smaller businesses.
Among his recommendations, he urged regulators to develop a simplified ESG disclosure template for small and medium-sized enterprises ahead of the 2030 deadline, with clear thresholds and phased implementation of more complex requirements.
He also called on the Financial Reporting Council, SEC, Nigerian Exchange, Central Bank of Nigeria, National Pension Commission and National Insurance Commission to harmonise their reporting requirements.
According to him, a unified reporting format and data platform would reduce duplication and enable companies to submit their sustainability information through a single reporting system.
He further urged the Federal Ministry of Power, the Nigerian Electricity Regulatory Commission and other relevant institutions to accelerate efforts to improve electricity supply, provide cheaper capital and promote cleaner energy.
These measures, he said, would help reduce both the cost of compliance and the environmental footprint of businesses.
Oyerinde also advised companies to begin preparing immediately by assigning ESG oversight responsibilities to their boards, establishing appropriate measurement systems and maintaining regular monitoring and reporting structures.
He stressed that sustainability should not be treated as a documentation exercise but must be reflected in the actual operations of businesses, their treatment of employees, environmental practices and corporate governance structures.
He said ESG reports should accurately reflect what companies do rather than serve merely as promotional documents.
‘ESG should strengthen private sector, national economy’
The NECA director-general maintained that Nigeria should approach ESG adoption as a tool for improving business competitiveness, rather than treating it solely as another regulatory burden.
He said the period leading to 2030 presented an opportunity to build businesses capable of attracting investment, protecting workers, managing environmental risks, creating employment and competing effectively in domestic and international markets.
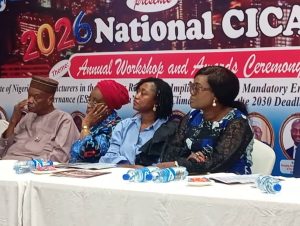
Oyerinde reaffirmed NECA’s commitment to working with government, regulators, organised labour, the media and other stakeholders to ensure that the transition to mandatory sustainability reporting strengthens the private sector and the Nigerian economy.


Comment here